Nasdaq Futures Rebound After AI Sell-Off as Oil Slips: What Traders Need to Know Today
 Markets are opening the week on a calmer footing. Nasdaq futures rebounded 1.3% and S&P 500 futures added 0.8% on Monday, 19 October 2026, after the tech-heavy index suffered its worst week since the April 2025 tariff shock. Oil eased from a five-month high as Washington paused new sanctions on Russia, while Treasuries, gold, and Bitcoin all edged higher.
The relief may be fragile. A heavy week of megacap earnings, elevated inflation, a hawkish-leaning Federal Reserve, and the 3 November US midterms are all converging. Here is what traders need to know before the opening bell.
US stocks: Nasdaq futures bounce after the AI sell-off
The rebound follows a bruising week for the AI trade. The Nasdaq 100 fell 5.5% over the five sessions, and on Friday, the S&P 500 lost 1.1%, while the Nasdaq Composite dropped 2.1%. The Dow held up better, slipping just 0.3%.
Chipmakers took the hardest hit. A widely followed semiconductor index logged its longest losing streak since 2008, and the VIX volatility gauge posted its sharpest jump since June. Cloud provider CoreWeave, which is backed by Nvidia, was among the most heavily sold names.
The driver is a growing question mark over AI spending. Investors want proof that the huge sums going into data centres will generate adequate returns, and worries over wider credit spreads at AI infrastructure firms added to the pressure. Nvidia CEO Jensen Huang struck a calm tone, telling investors the turbulence would pass and urging them to focus on the technology’s long-term value.
For traders, the key question is whether Monday’s bounce is the start of a recovery or a relief rally within a deeper correction. Several strategists see room for dip-buying, but others expect the AI wobble to keep tech volatility high and spill into the wider market.
Oil: Russia sanctions waiver pulls Brent off five-month highs
Brent crude fell 1.8% to around $107.90 a barrel, and WTI dropped 1.6% to about $97.40 in early trading. On Friday, Brent briefly hit $110 for the first time since May.
The main trigger was President Trump’s executive order putting broad new sanctions and tariffs on Russia on hold, days before they were due to take effect. The measures fall under the Graham Act, signed last month to pressure Moscow over the war in Ukraine. The waiver could free up more Russian energy exports and follows a separate diesel supply deal with Russia aimed at lowering US fuel prices before the midterms. Secretary of State Marco Rubio said the administration will take up to 60 days to assess the economic impact.
The supply picture remains tight, though. Analytics firm Kpler estimates Gulf crude flows dropped to roughly 8.5 million barrels per day on a seven-day average last week, down from over 20 million the week before, after at least 10 incidents involving commercial vessels. Shipping risk around the Strait of Hormuz and Egypt’s offer of security support to Saudi Arabia against the Houthis keep the geopolitical premium elevated.
What this means for traders: oil is being pulled between a policy-driven supply boost and a fragile Middle East. Expect sharp, headline-driven moves in both directions.
Asia: mixed session
Asian markets were mixed as tech volatility continued. The MSCI Asia Pacific Index trimmed early losses to trade around 0.2% lower.
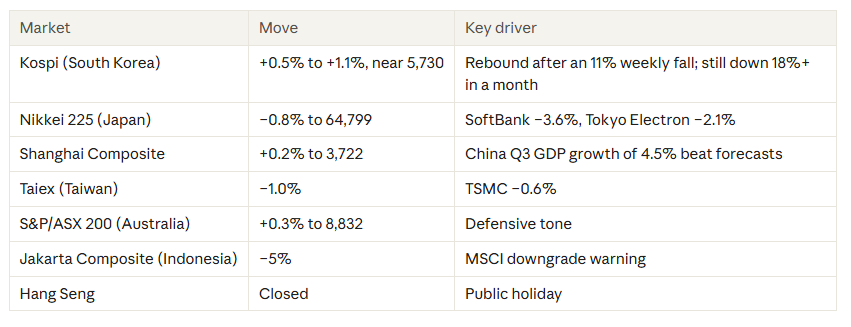 MSCI warned that it may strip the country of emerging-market status, which could force passive funds to sell. The market is now down about 44% this year, making it the worst performer globally.
In China, stronger third-quarter growth improves the chances that Beijing meets its annual target, but memory chipmaker CXMT still fell over 7% despite upbeat guidance, a sign that chip sentiment remains weak across the region.
Bonds, gold, FX and crypto: safe havens in demand
- Treasuries. The 10-year yield dipped one basis point to 5.06%, extending a 17 bp fall last week. Treasuries are tentatively regaining their safe-haven role, a risk for investors positioned for a deeper bond sell-off. Bond volatility remains elevated.
- Gold. Bullion rose 0.4% to $4,181 an ounce as traders scaled back bets on a Fed rate hike this month following Friday’s remarks from Fed Chair Kevin Warsh.
- Forex. The euro softened against most G10 currencies after weekend protests across France, which also weighed on French bond futures and European equity futures. EUR/USD traded near 1.1231, while USD/JPY held around 158.09.
- Crypto. Bitcoin climbed above $82,000, gaining between 0.7% and 2% during the Asian session as risk appetite steadied.
What traders should watch this week
Big Tech earnings will decide whether last week’s AI sell-off was an overreaction or an early warning.
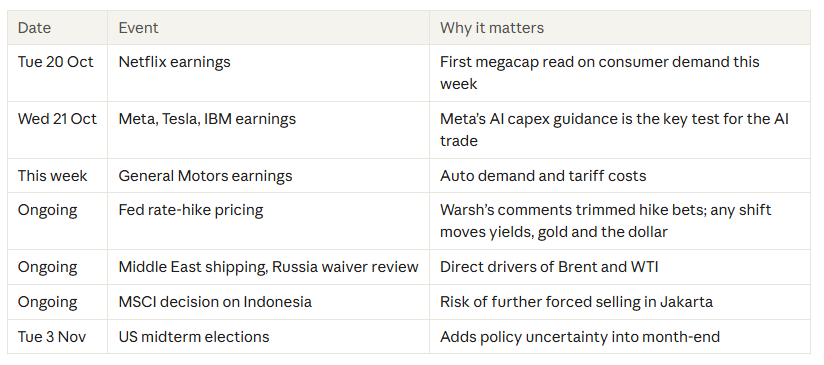 Three things to keep in mind:
- Volatility is elevated. With the VIX and bond volatility both raised, wider swings and gaps around earnings releases are likely. Review position sizes and stop-loss levels.
- Watch the AI capex message. Guidance on data-centre spending from Meta could move the Nasdaq 100, chip stocks, and Asian tech indices such as the KOSPI and TAIEX together.
- Oil is headline-driven. Prices can swing sharply on Middle East or Russia news, so stay close to the news flow.
Publication date:
2026-10-19 10:36:59 (GMT)

